Private Health Insurance Strategy: The Ultimate Guide for 2026
Navigating the healthcare system can be a daunting task for anyone trying to secure their financial and physical future. With medical costs rising globally, relying solely on basic or public healthcare networks is often a risky decision.
This is exactly why having a robust Private Health Insurance plan is more critical today than ever before. It serves as your primary defense against exorbitant hospital bills and long waiting times for crucial medical treatments.
In this comprehensive guide, we will explore every aspect of Private Health Insurance. From understanding the different types of plans to selecting the right coverage for your family, this article will equip you with the knowledge you need.
What Is Private Health Insurance?
At its core, Private Health Insurance is a health policy provided by a private entity rather than a state or federal government. These private entities are commercial insurance companies that calculate your risk and charge a premium accordingly.
When you purchase Private Health Insurance, you are entering into a legal contract with the insurance provider. You agree to pay a monthly or annual premium, and in return, the insurer agrees to pay a portion of your covered medical expenses.
Unlike public healthcare options, Private Health Insurance offers a vast array of choices regarding doctors, hospitals, and specialized treatments. It puts you in the driver’s seat of your own healthcare journey.
The Difference Between Public and Private Health Insurance
Understanding the contrast between public systems and Private Health Insurance is the first step to making an informed decision. Public health insurance is typically funded by taxes and managed by the government.
While public options provide essential coverage, they often come with significant limitations. Patients frequently experience long wait times for elective surgeries and specialist consultations.
Conversely, Private Health Insurance usually grants you immediate access to top-tier medical professionals. It bridges the gap between basic care and premium, expedited medical services.
Why You Need a Solid Private Health Insurance Strategy
Managing your healthcare requires foresight and planning, much like managing a financial investment portfolio. To safeguard your wealth from medical emergencies, implementing a strong Private Health Insurance Strategy is absolutely essential.
Without a strategy, you might end up paying for a policy that lacks the specific coverage you actually need. A well-planned Private Health Insurance approach ensures you get the maximum value for your premium dollars.
It protects you from financial ruin in the event of a catastrophic illness or sudden injury. Having Private Health Insurance is not just about health; it is a fundamental pillar of modern financial planning.
Access to Shorter Wait Times and Premium Facilities
One of the most significant benefits of Private Health Insurance is the ability to bypass long public waiting lists. When you need a specialist, private coverage allows you to book an appointment almost immediately.
Furthermore, Private Health Insurance often covers stays in private hospital rooms rather than shared public wards. This ensures a more comfortable, quiet, and dignified recovery environment.
Comprehensive Coverage Options
Another major advantage is the breadth of services covered by Private Health Insurance. While basic plans cover hospitalization, premium plans offer much more.
Many Private Health Insurance policies cover alternative therapies, chiropractic care, and extensive mental health services. You can also customize your plan to include dental and vision coverage.
Types of Private Health Insurance Plans
When shopping for Private Health Insurance, you will quickly notice that not all plans are structured the same way. The market is divided into several specific network types.
Understanding these networks is crucial before buying Private Health Insurance. Your choice will dictate which doctors you can see and how much you will pay out of pocket.
Health Maintenance Organizations (HMOs)
HMO plans are a very common type of Private Health Insurance. They require you to choose a Primary Care Physician (PCP) who coordinates all your healthcare needs.
If you need to see a specialist, your PCP must issue a referral first. Furthermore, HMO Private Health Insurance strictly requires you to use doctors and hospitals within their specific network.
If you go out of network, your HMO plan will generally not cover the costs, except in a true medical emergency. The trade-off is that HMO plans usually have lower monthly premiums.
Preferred Provider Organizations (PPOs)
PPO plans offer much more flexibility within the Private Health Insurance landscape. You do not need to select a primary care doctor, and you do not need referrals to see specialists.
With PPO Private Health Insurance, you can visit any healthcare provider you choose. However, you will pay significantly less if you use providers within the insurance company’s “preferred” network.
Because of this unparalleled flexibility, PPO plans are typically the most expensive type of Private Health Insurance. They are ideal for individuals who travel frequently or want total control over their healthcare.
Exclusive Provider Organizations (EPOs)
EPO plans are a hybrid model in the Private Health Insurance market. Like an HMO, an EPO requires you to use only the doctors and hospitals within their designated network.
However, similar to a PPO, EPO Private Health Insurance does not usually require you to get a referral to see a specialist. If you go out of network with an EPO, you will bear the full cost of the medical bill.
Point of Service (POS) Plans
POS plans blend the features of both HMO and PPO Private Health Insurance. You are required to choose a primary care doctor who directs your care and provides specialist referrals.
But, like a PPO, a POS Private Health Insurance plan allows you to go out of network for care. Keep in mind that out-of-network care will result in much higher out-of-pocket costs and deductibles.
How to Choose the Best Private Health Insurance
Selecting the right Private Health Insurance policy requires a deep dive into your personal medical needs and financial capabilities. It is not a one-size-fits-all situation.
You must carefully balance the cost of your monthly premium against your potential out-of-pocket expenses. Finding the sweet spot is the key to maximizing your Private Health Insurance.
Evaluating Your Monthly Premiums
The premium is the set amount you pay every month to keep your Private Health Insurance active. If you are young and healthy, you might opt for a plan with a lower premium.
However, low-premium Private Health Insurance usually comes with a higher deductible. You must ensure you have enough savings to cover that deductible if a sudden illness strikes.
Understanding Deductibles and Out-of-Pocket Costs
The deductible is the amount you must pay out of your own pocket before your Private Health Insurance starts paying its share. High-deductible plans are common for catastrophic coverage.
Once you meet your deductible, you will still share costs through copayments or coinsurance. Always check the “Out-of-Pocket Maximum” on any Private Health Insurance policy, as this is the absolute most you will pay in a calendar year.
The Role of Employer-Sponsored Private Health Insurance
In the United States, the most common way to obtain Private Health Insurance is through an employer. Employer-sponsored plans are considered private because they are managed by commercial insurance companies.
The massive benefit here is that employers usually subsidize a large portion of the Private Health Insurance premium. This makes it significantly cheaper than buying an individual plan on the open market.
If your employer offers Private Health Insurance, it is almost always the most cost-effective route to take. Human resources departments usually negotiate better group rates than individuals can get on their own.
Purchasing Individual Private Health Insurance
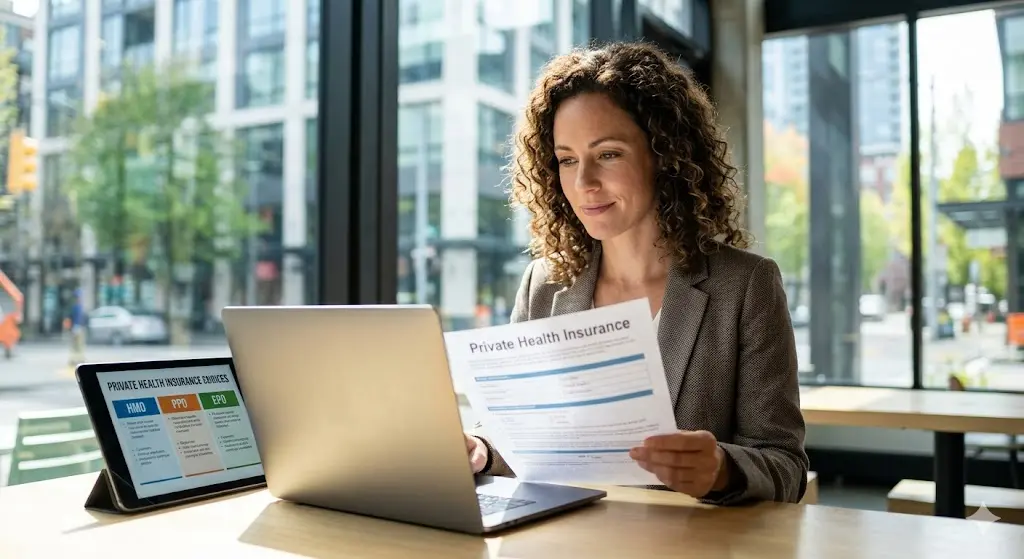
If you are self-employed, an independent contractor, or your employer does not offer benefits, you must buy individual Private Health Insurance. This means purchasing directly from an insurance carrier or a broker.
Navigating the individual Private Health Insurance market requires careful attention to detail. You are entirely responsible for the monthly premiums, though you may qualify for government subsidies based on your income.
Navigating the Health Insurance Marketplace
The Affordable Care Act (ACA) created federal and state marketplaces where you can compare Private Health Insurance plans. These marketplace plans must cover essential health benefits.
When buying Private Health Insurance through the marketplace, plans are categorized by metal tiers: Bronze, Silver, Gold, and Platinum. Bronze plans have the lowest premiums but highest out-of-pocket costs, while Platinum plans are the exact opposite.
Common Misconceptions About Private Health Insurance
There are many myths surrounding Private Health Insurance that can prevent people from getting the care they need. One common myth is that private insurance won’t cover pre-existing conditions.
Under current ACA laws, marketplace Private Health Insurance plans cannot legally deny you coverage or charge you more due to a pre-existing medical condition.
Another misconception is that Private Health Insurance covers 100% of your medical bills. In reality, almost all plans require cost-sharing through deductibles and copays, making it vital to read the fine print before signing any contract.
Conclusion
Securing the right coverage is one of the most important financial and medical decisions you will ever make. Private Health Insurance provides a critical layer of protection against skyrocketing medical costs and ensures you have access to the best doctors and facilities without enduring agonizing wait times. By understanding the differences between HMOs, PPOs, and EPOs, you can tailor your coverage to fit your lifestyle and budget perfectly. Always remember to calculate your total out-of-pocket exposure, not just your monthly premium, to avoid hidden financial traps. Take the time to evaluate your employer options or navigate the individual marketplace carefully, so you can build a safety net that protects both your health and your life savings.
FAQ
Frequently Asked Questions (FAQ)
1. Does Private Health Insurance cover pre-existing conditions?
Yes. Under the Affordable Care Act (ACA), any Private Health Insurance plan purchased through the federal or state marketplace must cover pre-existing conditions without charging you higher premiums or denying coverage.
2. What is the difference between an HMO and a PPO in Private Health Insurance?
An HMO requires you to use a primary care doctor and get referrals to see specialists within a strict network. A PPO offers more freedom, allowing you to see any doctor or specialist without a referral, though staying in-network is cheaper.
3. Is Private Health Insurance tax-deductible?
If you are self-employed, you may be able to deduct 100% of your Private Health Insurance premiums. For others, medical expenses (including premiums) may be deductible if they exceed a certain percentage of your adjusted gross income.
4. What happens if I use an out-of-network doctor?
If you have an HMO or EPO Private Health Insurance plan, you will likely have to pay the entire bill yourself. If you have a PPO or POS plan, the insurance will cover a portion, but your out-of-pocket costs will be significantly higher than if you stayed in-network.
5. Can I buy Private Health Insurance at any time of the year?
Generally, you can only buy individual Private Health Insurance during the annual Open Enrollment Period. However, if you experience a qualifying life event (like losing a job, getting married, or having a baby), you may qualify for a Special Enrollment Period.
Protect Your Health and Wealth Today!
Don’t wait until a medical crisis strikes to find out your current coverage is inadequate. Review your options and secure the best Private Health Insurance plan tailored to your specific needs. Click here to compare top-tier policies, get a free quote, and take total control of your healthcare journey today!