Medicare Supplement Plans Strategy: The Complete Guide to Coverage [Update 2026]
Navigating the American healthcare system can feel incredibly overwhelming for seniors today. As medical costs continue to rise, relying solely on Original Medicare is often not enough to protect your life savings.
This is exactly why understanding Medicare Supplement Plans is crucial for your long-term financial and physical well-being. These plans act as a safety net, catching the expensive medical bills that standard government insurance leaves behind.
In this comprehensive guide, we will break down everything you need to know about Medicare Supplement Plans. From understanding how they work to choosing the best option for your specific needs, we have you covered.
What Are Medicare Supplement Plans?

Medicare Supplement Plans, also widely known as Medigap, are private health insurance policies sold by specialized insurance companies. Their primary purpose is to fill the “gaps” in coverage left by Original Medicare (Part A and Part B).
Original Medicare pays for a significant portion of hospital and medical services, but it does not cover everything. You are still responsible for copayments, coinsurance, and deductibles, which can quickly add up to thousands of dollars.
This is where Medicare Supplement Plans step in to save the day. When you have one of these plans, Original Medicare pays its share of the Medicare-approved amount for covered healthcare costs, and then your Medigap policy pays its share.
It is important to note that Medicare Supplement Plans are strictly regulated by the federal and state governments. This means that a Plan G from one insurance company offers the exact same basic benefits as a Plan G from another company.
The True Value of Medicare Supplement Plans
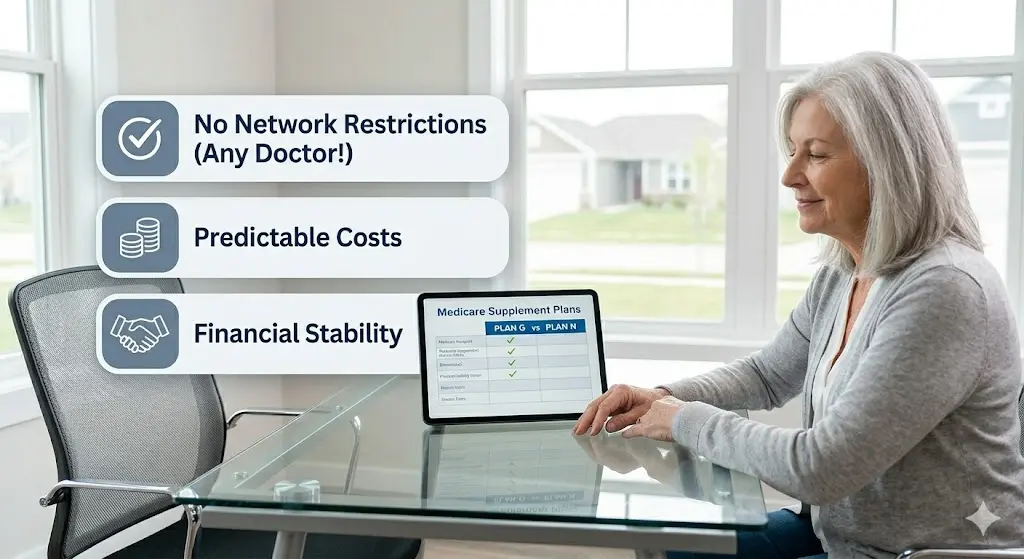
The true value of Medicare Supplement Plans lies in the financial predictability they offer. Instead of worrying about unpredictable hospital bills, you pay a set monthly premium.
This allows seniors to budget their healthcare costs accurately. With Medicare Supplement Plans, you can visit any doctor or hospital in the United States that accepts Medicare patients.
There are no restrictive networks like HMOs or PPOs to worry about. If a specialist takes Medicare, they will automatically accept your Medicare Supplement Plans.
How Do Medicare Supplement Plans Work?
To fully grasp how Medicare Supplement Plans function, you must first understand the foundation of your healthcare: Original Medicare. You must be actively enrolled in both Medicare Part A (Hospital Insurance) and Part B (Medical Insurance) to buy a Medigap policy.
Once you purchase one of the available Medicare Supplement Plans, you will pay a monthly premium to the private insurance company. This premium is in addition to the Part B premium you pay directly to Medicare.
When you receive medical care, your healthcare provider will send the bill directly to Medicare. Medicare processes the claim and pays its approved portion of the bill.
Afterward, Medicare automatically forwards the remaining balance to your Medigap insurance company. Your Medicare Supplement Plans will then pay their designated portion, depending on the specific letter plan you chose.
What Is Not Covered by Medicare Supplement Plans?
While Medicare Supplement Plans are incredibly comprehensive for hospital and doctor visits, they do not cover everything. It is vital to know their limitations to avoid unexpected out-of-pocket expenses.
Most Medicare Supplement Plans do not cover long-term care, such as non-skilled care in a nursing home. They also generally do not cover routine vision care, eyeglasses, or routine dental care.
Furthermore, hearing aids and private-duty nursing are entirely excluded from Medicare Supplement Plans. Perhaps most importantly, modern Medigap policies do not include prescription drug coverage.
If you want coverage for your medications, you must purchase a separate Medicare Part D Prescription Drug Plan. Relying only on Medicare Supplement Plans for pharmacy needs will leave you unprotected.
The Standardized Letters: A Deep Dive into Medicare Supplement Plans
In most states, Medicare Supplement Plans are standardized and named by letters, ranging from Plan A to Plan N. Each letter represents a different level of standardized coverage.
Because the benefits are standardized by the government, shopping for Medicare Supplement Plans is much easier. You are essentially comparing prices and customer service between different insurance carriers.
Let’s take a detailed look at the most popular Medicare Supplement Plans available on the market today.
Medicare Supplement Plan F: The Comprehensive Giant
Historically, Plan F has been the most popular of all the Medicare Supplement Plans. It offers the most comprehensive coverage, paying for almost all Medicare-approved out-of-pocket costs.
If you have Plan F, you generally pay zero out-of-pocket for doctor visits and hospital stays. It covers both the Part A and Part B deductibles entirely.
However, there is a catch regarding these specific Medicare Supplement Plans. Plan F is only available to individuals who became eligible for Medicare before January 1, 2020.
If you became eligible after this date, you cannot purchase Plan F.
Medicare Supplement Plan G: The Modern Favorite
For newly eligible beneficiaries, Plan G has quickly become the gold standard among Medicare Supplement Plans. It offers almost identical coverage to Plan F, with one single exception.
Plan G does not cover the Medicare Part B annual deductible. Once you pay this relatively small deductible out of pocket, Plan G functions exactly like Plan F for the rest of the year.
Because of this slight difference, the monthly premiums for Plan G are often significantly lower than Plan F. Many financial advisors consider Plan G the best overall value among Medicare Supplement Plans.
Medicare Supplement Plan N: The Budget-Friendly Option
If you want lower monthly premiums and don’t mind small copayments, Plan N is an excellent choice among Medicare Supplement Plans. It covers the Part A deductible but requires cost-sharing for routine visits.
With Plan N, you may pay up to a $20 copayment for some office visits. You may also face up to a $50 copayment for emergency room visits that do not result in inpatient admission.
Additionally, Plan N is one of the few Medicare Supplement Plans that does not cover Medicare Part B excess charges. Despite these minor costs, its low premiums make it highly attractive for healthy seniors.
The Financial Strategy Behind Medicare Supplement Plans
Managing your healthcare costs in retirement requires a solid financial strategy. Choosing the right Medicare Supplement Plans is similar to managing a diverse financial portfolio or planning long-term investments.
To protect your retirement savings, implementing a solid Medicare Supplement Plans Strategy helps beneficiaries understand coverage details and avoid unexpected out-of-pocket costs.
Similarly, deeply analyzing your Medicare Supplement Plans prevents you from experiencing sudden financial shocks in your medical bills. You need a reliable system to ensure your wealth is protected from sudden health crises.
Calculating the True Cost of Medicare Supplement Plans
When comparing Medicare Supplement Plans, you must look beyond just the monthly premium. You need to calculate your total potential healthcare liability for the entire year.
Insurance companies use three different pricing methods for Medicare Supplement Plans: community-rated, issue-age-rated, and attained-age-rated. Understanding these pricing models is crucial.
Community-rated Medicare Supplement Plans charge the same premium to everyone in the same area, regardless of age. Issue-age-rated policies base your premium on your age when you first buy the policy.
Attained-age-rated Medicare Supplement Plans are the most common. The premium starts lower but automatically increases every year as you get older.
When is the Best Time to Enroll in Medicare Supplement Plans?
Timing is everything when it comes to purchasing Medicare Supplement Plans. There is a specific window of time that offers you the most protection and the best prices.
This period is called the Medigap Open Enrollment Period. It lasts for six months and strictly begins on the first day of the month in which you are both 65 or older and enrolled in Medicare Part B.
During this six-month window, you have guaranteed issue rights for any of the Medicare Supplement Plans sold in your state. This is the most powerful right you have as a Medicare beneficiary.
The Power of Guaranteed Issue Rights
Guaranteed issue rights mean that an insurance company cannot refuse to sell you any Medicare Supplement Plans they offer. They also cannot charge you higher premiums based on your past or present health problems.
During this period, pre-existing conditions do not matter. You bypass medical underwriting entirely when selecting your Medicare Supplement Plans.
If you miss this Medigap Open Enrollment Period, buying Medicare Supplement Plans becomes much more difficult. The insurance company can subject you to rigorous medical underwriting.
They will review your medical history, current medications, and past surgeries. Based on this review, they can legally deny your application for Medicare Supplement Plans or charge you significantly higher rates.
Medicare Supplement Plans vs. Medicare Advantage
A common source of confusion is the difference between Medicare Supplement Plans and Medicare Advantage (Part C). They are completely different types of insurance and cannot be used together.
Medicare Advantage plans are an alternative to Original Medicare. They are all-in-one plans that usually include health and drug coverage, operating much like traditional HMOs or PPOs.
While Advantage plans often have zero-dollar premiums, they come with strict network restrictions. You must use doctors within their network, or you will pay heavy out-of-pocket fees.
Medicare Supplement Plans, on the other hand, offer total freedom. As long as the doctor accepts Original Medicare, your Medigap policy will work, regardless of where you are in the United States.
Furthermore, Medicare Supplement Plans have no required referrals to see a specialist. Advantage plans frequently require you to see a primary care doctor before visiting a specialist.
How to Choose the Right Medicare Supplement Plans for Your Needs
Selecting the perfect policy from the various Medicare Supplement Plans requires a careful assessment of your health and lifestyle. Start by evaluating your current health status and family medical history.
If you have chronic conditions or anticipate frequent doctor visits, robust Medicare Supplement Plans like Plan G are usually the safest bet. The higher premium is offset by the lack of medical bills.
Next, consider your lifestyle and travel habits. If you travel frequently across different states, the nationwide acceptance of Medicare Supplement Plans is absolutely essential.
Finally, compare quotes from multiple top-rated insurance carriers. Since the benefits of Medicare Supplement Plans are standardized, there is no reason to overpay for the exact same Plan G from a different company.
Working with an independent, licensed Medicare broker can streamline this process. They can pull quotes for all available Medicare Supplement Plans in your zip code in minutes.
Conclusion
Securing your financial future during retirement heavily depends on how well you manage your healthcare costs. Medicare Supplement Plans provide the ultimate peace of mind, ensuring that an unexpected illness does not drain your hard-earned life savings. By understanding the standardized letters, the importance of the Open Enrollment Period, and how these policies interact with Original Medicare, you can make a highly informed decision.
Remember that while Plan G offers the most robust coverage for new beneficiaries, Plan N is an excellent alternative for those seeking lower monthly premiums. Take the time to compare prices, avoid late enrollment penalties, and choose a plan that allows you to enjoy your retirement without the constant fear of medical debt.
FAQ
Frequently Asked Questions (FAQ)
1. Can my doctor refuse to accept my Medicare Supplement Plans?
No. If your doctor accepts Original Medicare, they are legally required to accept your standardized Medigap policy, regardless of which insurance company issued it.
2. Do Medicare Supplement Plans cover prescription drugs?
No, modern Medigap policies do not include prescription drug coverage. You must purchase a standalone Medicare Part D plan to cover your medications.
3. Can I be dropped from my Medicare Supplement Plans if I get sick?
As long as you continue to pay your monthly premiums on time, your Medigap policy is guaranteed renewable. The insurance company cannot cancel your coverage due to declining health.
4. Are Medicare Supplement Plans family policies?
No, Medigap policies only cover one individual. If both you and your spouse need coverage, you must each purchase separate, individual policies.
5. What happens if I move to a different state?
Since Medigap policies are standardized federally (in most states), your coverage travels with you anywhere in the US. However, your monthly premium may adjust based on your new zip code.
Take Control of Your Healthcare Today!
Don’t wait until a medical emergency strikes to realize you have gaps in your coverage. Compare the best rates in your area right now and secure the perfect Medigap policy for your lifestyle. Contact a licensed independent agent today to get a free, no-obligation quote and start protecting your retirement savings!